
News
2023 Market Predictions


By Michael O’Connor, theislandinvestor.com
For me, investing is just a potent mix of optimism and paranoia - being optimistic about what the future holds but constantly paranoid about the landmines that you will undoubtedly trigger along the way.
Finding a balance between the two is key, but I have to admit, going into 2023, paranoia appears to have the upper hand.
Expectation vs Reality
Whether you are waiting on test results, or tentatively hovering over the phone for that all important call back from your potential new employer, it's the difference between expectation and reality that dictates the severity of your reaction.
Regardless of how bad the reality turns out to be, if your initial expectations were set apocalyptically low, your reaction will probably be positive and vice versa.
Financial markets work the same way. As I have said before, investing is never about things being objectively good or bad. The narrative is always based around better or worse. If the outlook for markets is exceptionally high and the performance falls even slightly below these expectations, prices will fall as a result. The fact that performance and growth is still strong in absolute terms is irrelevant if expectation were not met. With this in mind, in order to understand how markets will react in 2023, we must first analyse the market's expectations.
The Year Ahead
On the equity side, 12-month forward earnings projections for the S&P 500 are set at 5%. In other words, analysts predict American companies will grow their profits by 5% next year.
While this represents a significant slowdown in growth relative to what we have experienced since the pandemic pullback in early 2020, I view this as optimistic, given the considerable change in monetary and fiscal policy in 2022.
Q3 2022 earnings season looks likely to finish at 2% year-over-year growth, the weakest since the height of the pandemic. Ex-energy, performance becomes weaker still.
Looking ahead to Q4 2022, analysts are now predicting the first negative quarter since 2020, with profit growth falling to -2%. These Q4 earnings predications from the same analysts were as high as +9% as recently as June.
While expectations for ‘23 are still at plus 5% earnings growth, I wouldn’t be surprised to see 2023 earnings forecasts suffer the same faith as the Q4 2022 forecast.
In short, markets are a bit like the Irish weather, never believe the forecast.
As leading indicators continue to point towards a slowdown in economic activity, a base case of positive 2023 earnings growth becomes difficult to justify. In my view, this will result in some negative earnings surprises in the second half of 2023.
In Fixed Income markets, the Fed has reiterated its plan to hold rates higher for longer, and this expectation is reflected in markets. According to the market-implied Fed Funds Rate, investors are now expecting US short term interest rates to peak at 4.9% in six months and remain well above 4% into 2024.
In my view, the probability of the Fed maintaining a long pause as we enter more economically uncertain times is not as high as the market is predicting. I believe a pivot is likely before 2024 as earnings and labour markets weaken.
Summary
While the lows for multiples may already be in, a mild earnings recession in the second half of 2023 may result in a slow grind lower for the stock market.
This pullback in earnings and labour will prompt a pivot from the Fed, forcing them to cut rates in an attempt to avoid the re-emergence of the disinflationary forces that provoked a decade of QE through the 2010s.
While it is impossible to know the exogenous shocks that lie ahead, buying up short-term Treasuries and maintaining a tilt toward value-based equity will protect if the current economic slowdown persists.
For more tips on how to beat the market in 2023, simply go to www.theislandinvestor.com.

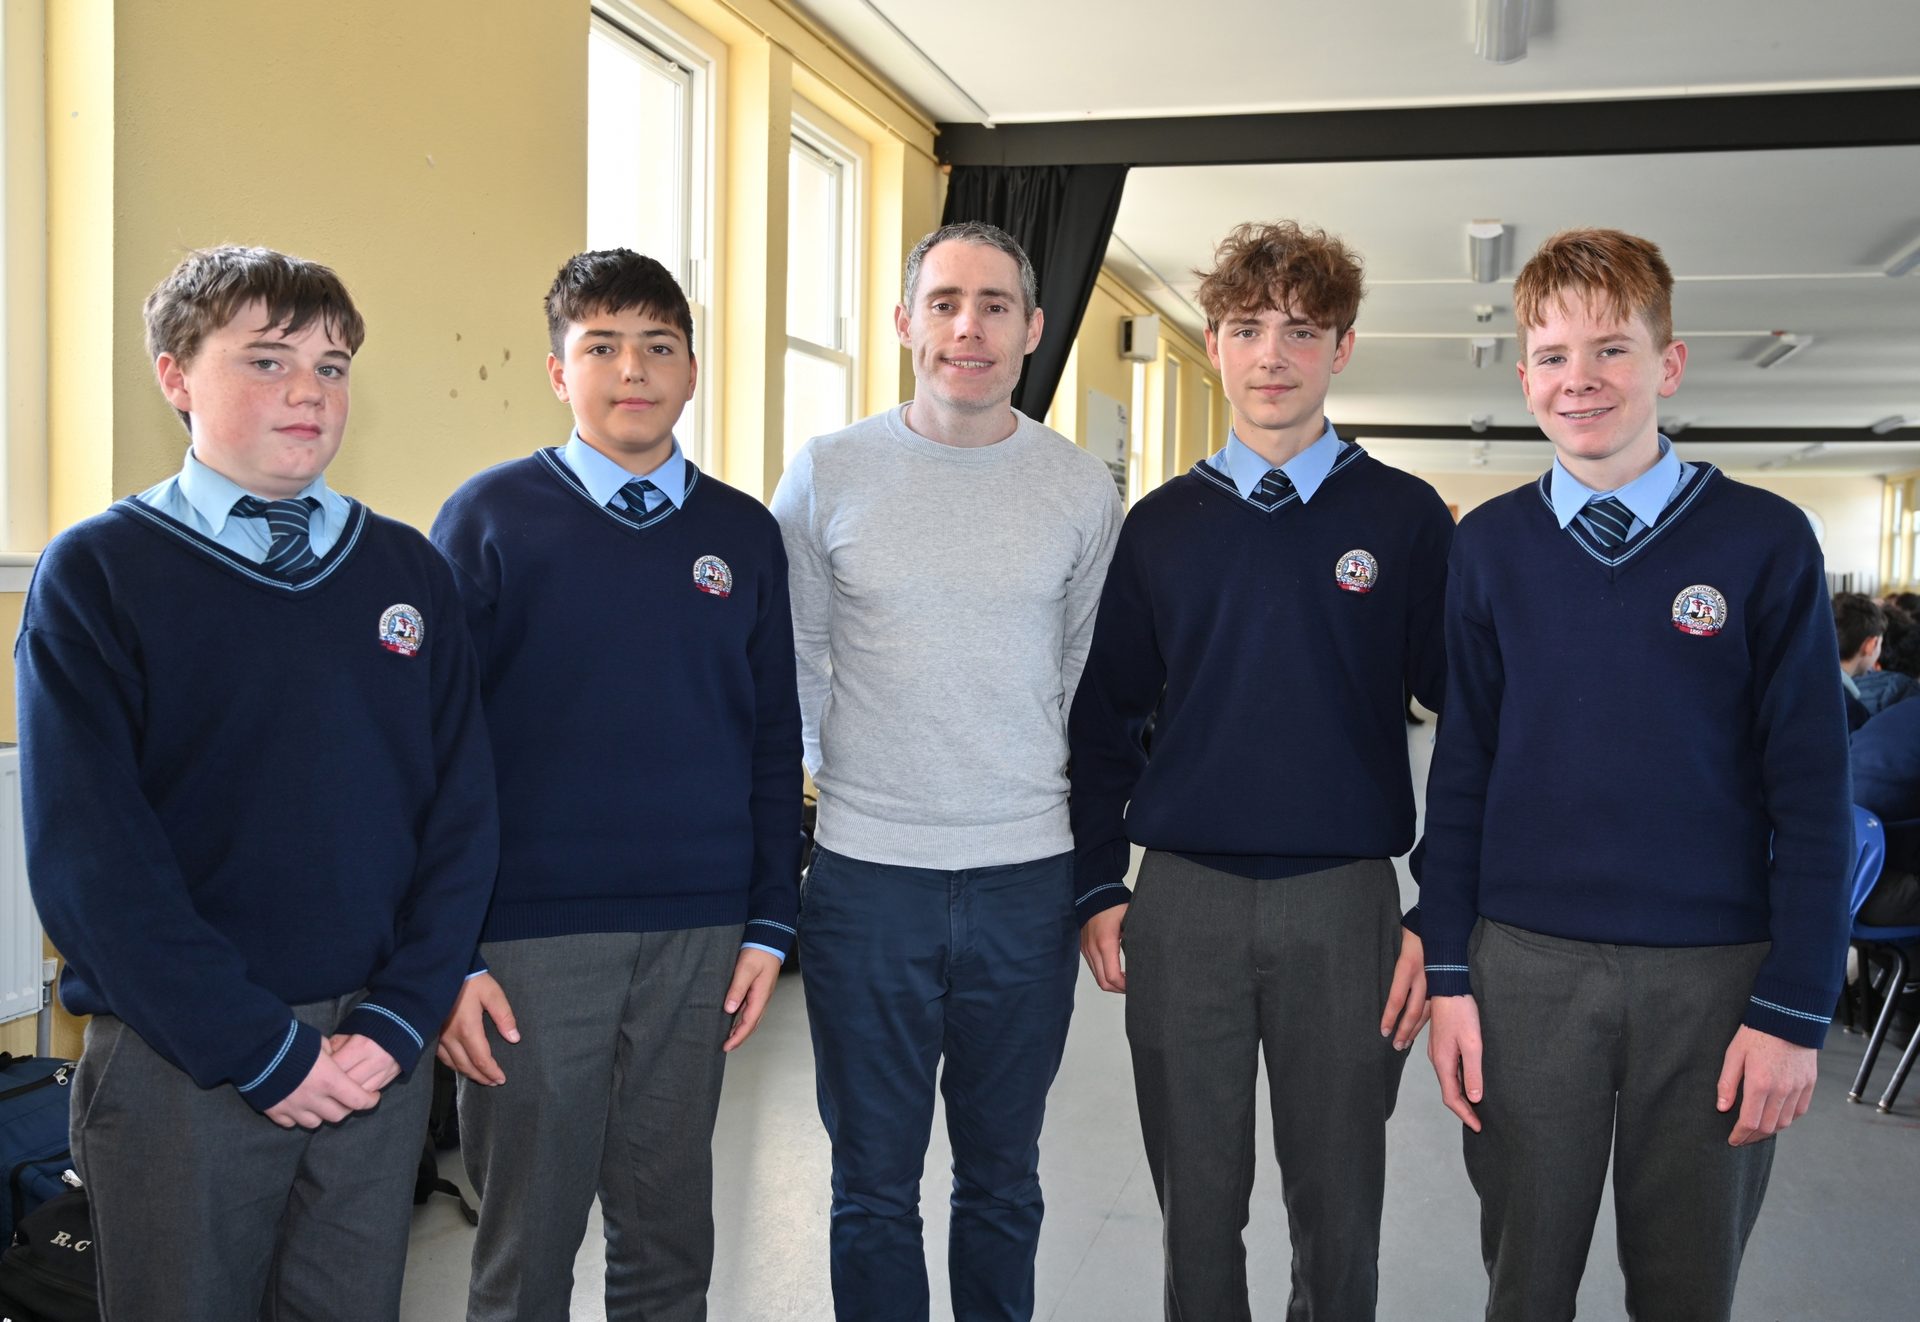
Paralympic legend Jason Smyth visits St Brendan’s
World renowned Paralympian and world record holder Jason Smyth paid a visit to St Brendan’s College on Wednesday afternoon as part of a high profile visit to Killarney.
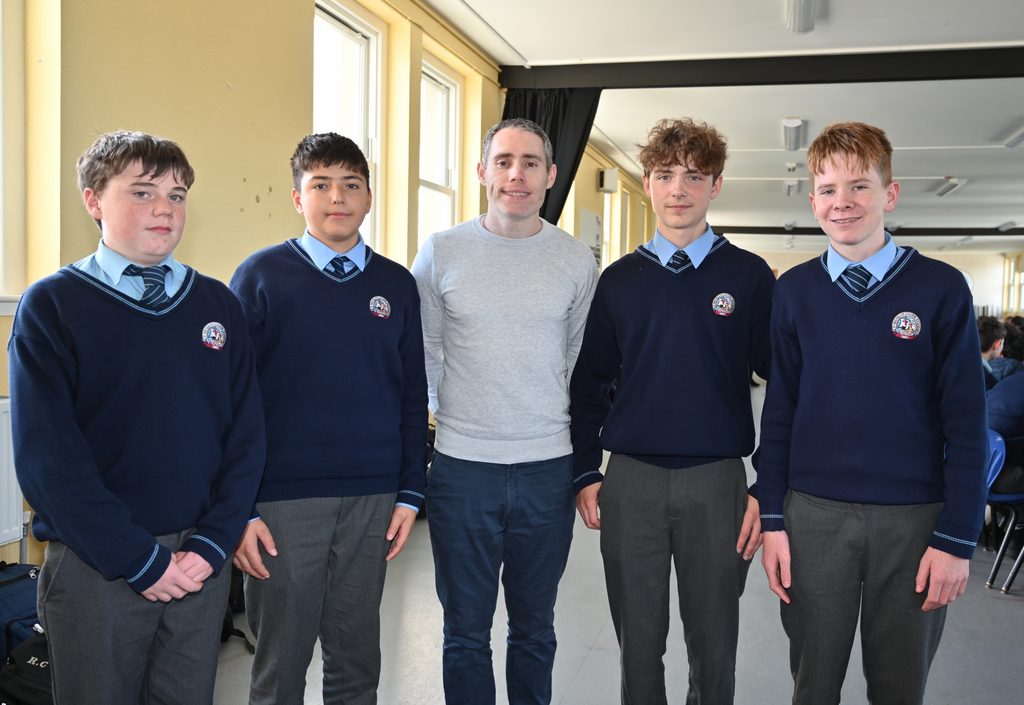
The six time Paralympic gold medallist spoke to second year students from St Brendan’s College, alongside students from neighbouring schools St Brigid’s Presentation Secondary School and Killarney Community College.
The interactive talk and interview took place ahead of World Sight Day, with the legendary sprinter sharing his personal journey with Stargardt disease, a genetic eye condition that left him legally blind at eight years old.
The Derry native, who holds the world record as the fastest Paralympian on earth over 100 metres, offered inspiring insights into overcoming physical adversity and achieving success at the highest level of world sport.
The school visit formed the opening leg of his Killarney schedule before he took centre stage later on Wednesday evening at The Killarney Plaza Hotel & Spa.
Smyth headlined An Evening with Paralympian Jason Smyth, an event organised by the Killarney Chamber of Tourism and Commerce as part of its winter schedule, sponsored by AIB.

Paralympic legend Jason Smyth visits St Brendan’s
Paralympic legend Jason Smyth visits St Brendan’s World renowned Paralympian and world record holder Jason Smyth paid a visit to...
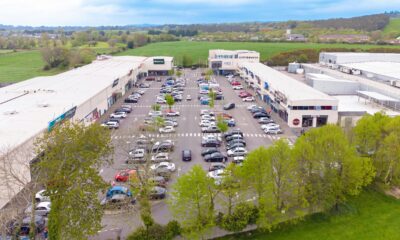

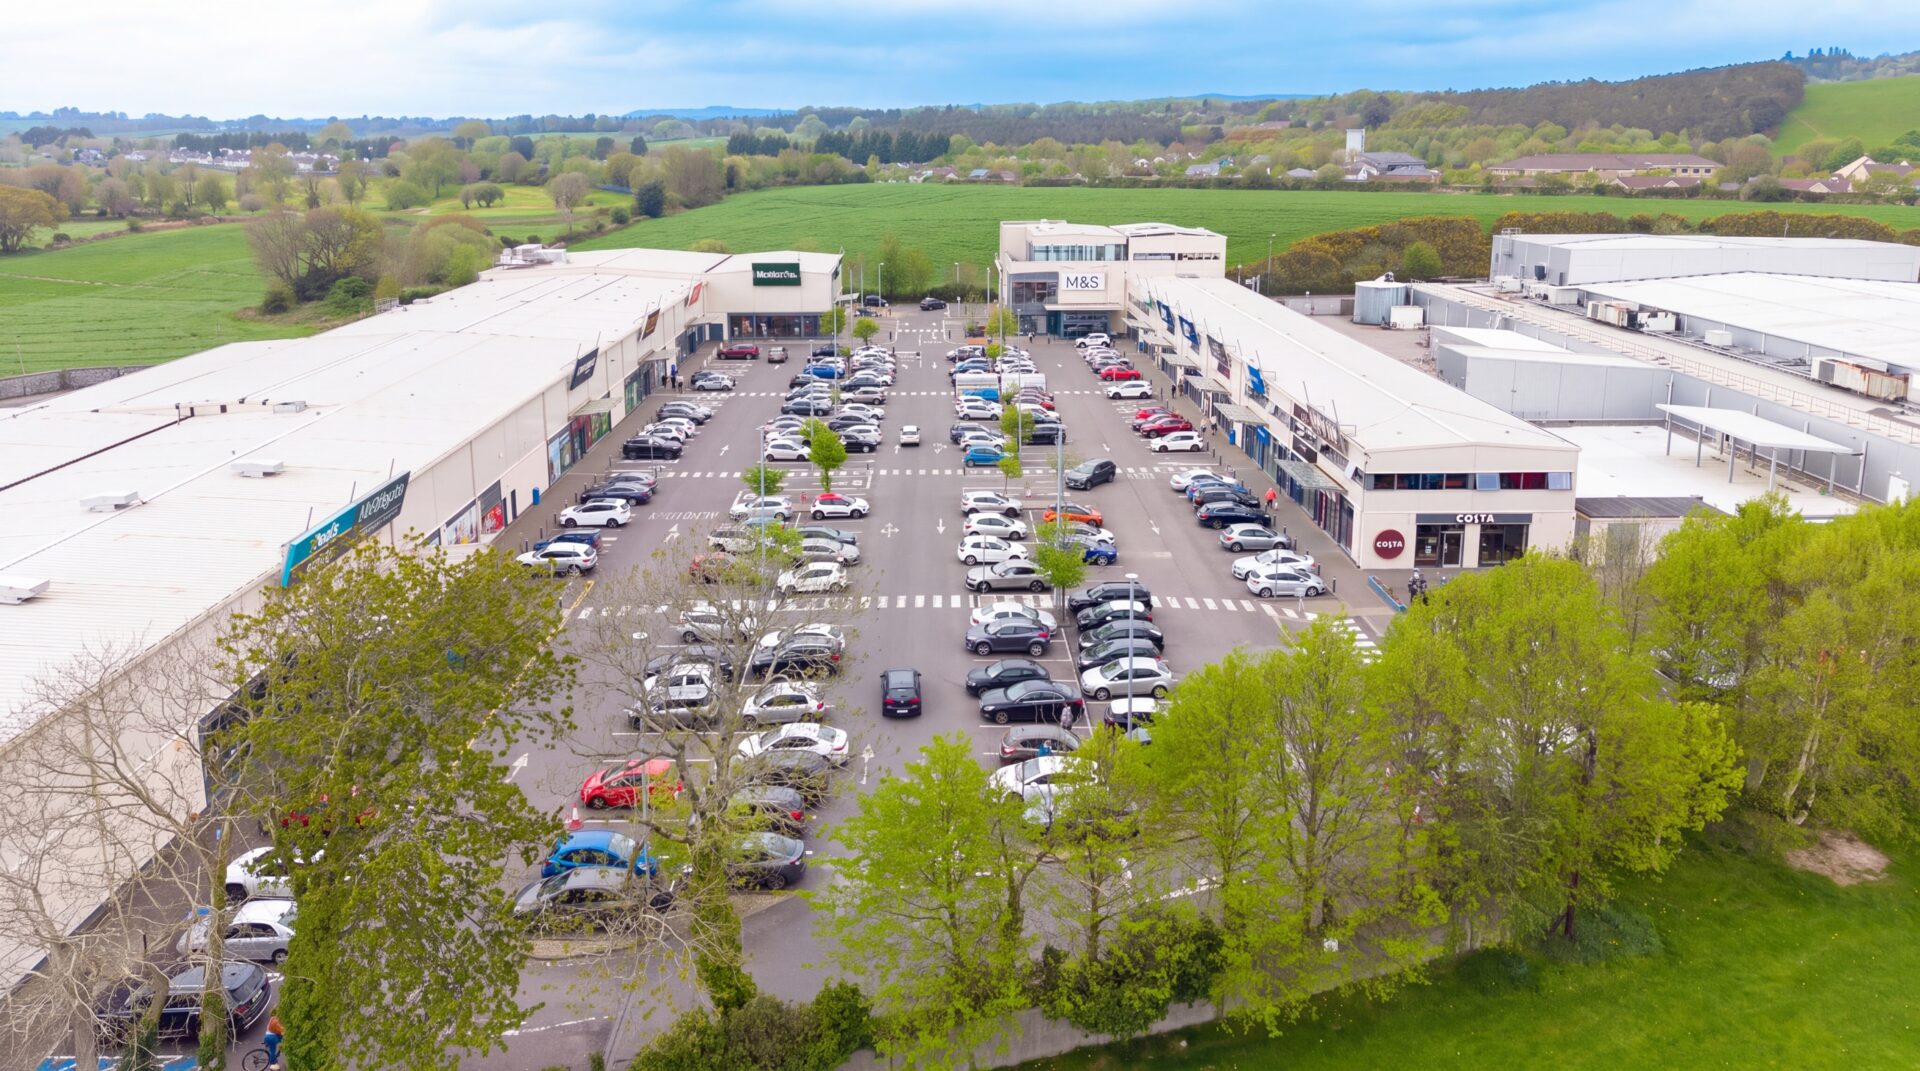
Deerpark Retail Park placed on market for fifteen million euro
Deerpark Retail Park in Killarney has officially been placed on the market with a guide price in excess of 15.4...
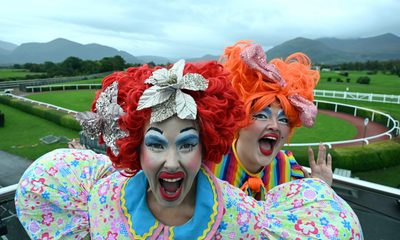

Killarney Racecourse to host first professional festive pantomime
Killarney Racecourse to host first professional festive pantomime A classic fairytale is set to receive a distinct Kerry makeover this festive...

Kerry artist explores identity at ANAM
Kerry artist explores identity at ANAM Kerry artist Felix Power is inviting the Killarney community to explore personal ideas of...

Town encouraged to wear bright colours for Kevin
Town encouraged to wear bright colours for Kevin The town of Killarney was encouraged to wear its brightest colours this...
